- Trending
- Comments
- Latest
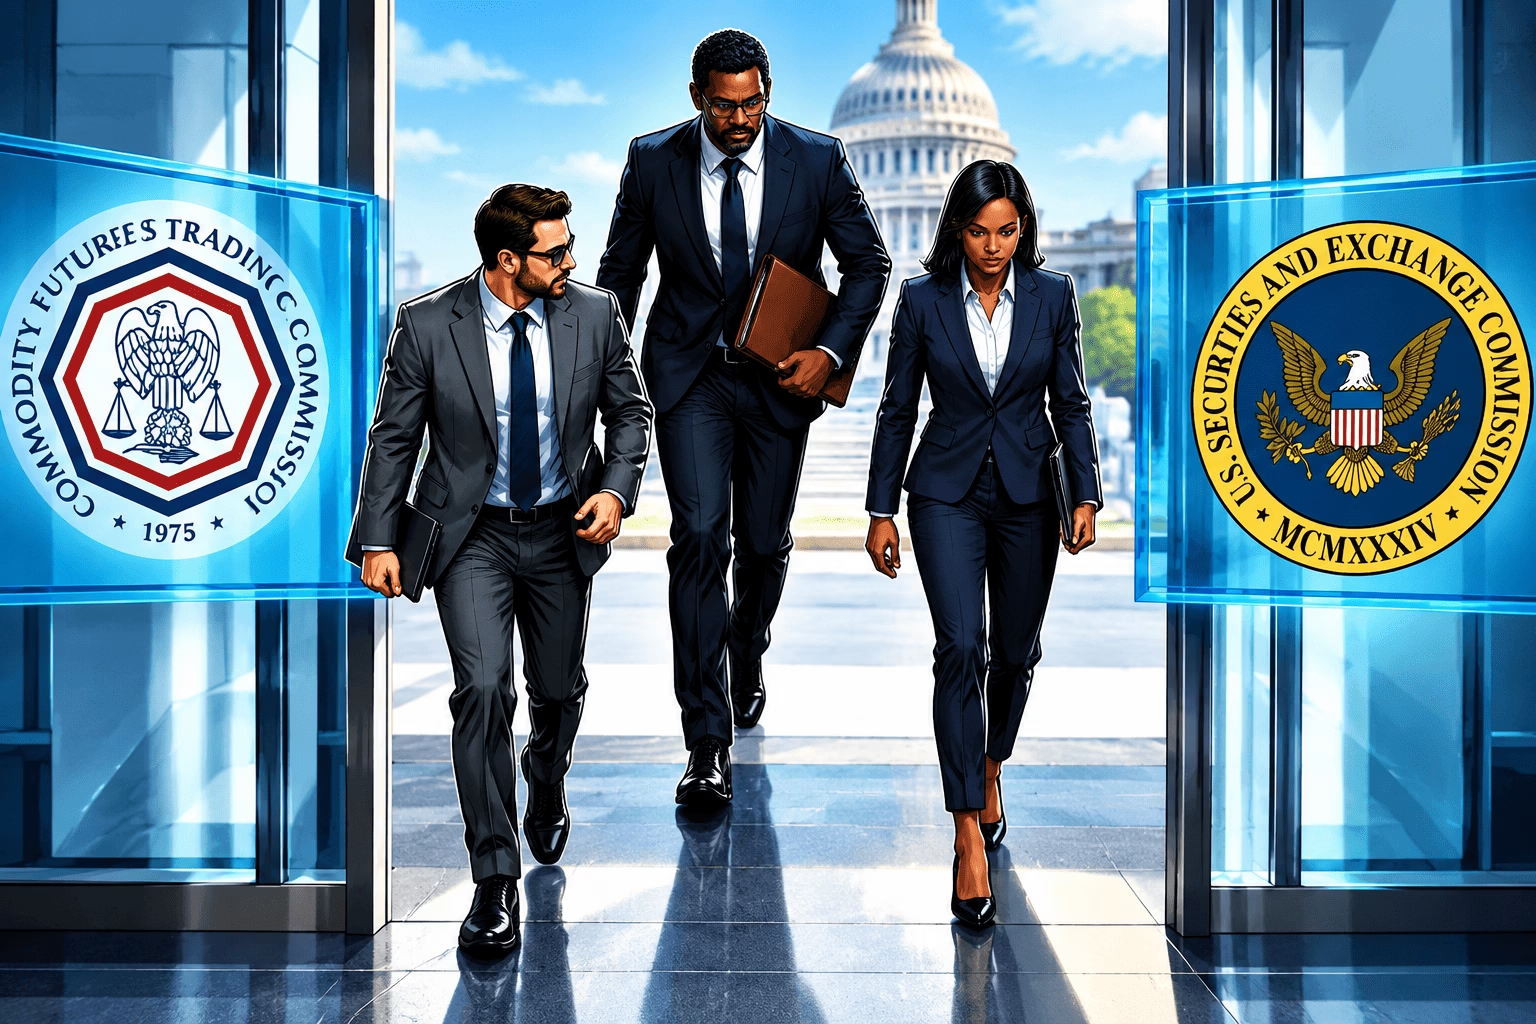
The SEC has cleared the way for tokenized U.S. stocks to trade onchain, approving a temporary exemption that lets select platforms run blockchain-based markets for equities, a move regulators call a first step toward reshaping how American securities are issued, traded and settled.
The developments arrive shortly after the U.S. Senate failed to advance the CLARITY Act, leaving regulators to pursue parts of their digital-asset agenda using existing statutory authority.
Speaking at the 2026 U.S. Treasury Market Conference on Sept. 22, Selig said the financial industry needs to prepare for a new market structure built around blockchain technology, artificial intelligence and 24-hour trading.
At the center of that transition is Tokenization, which converts rights to real-world assets into digital representations that can be recorded and transferred using blockchain infrastructure.
Selig argued that tokenized real-world assets could eventually serve as a foundation for a more efficient financial system. He pointed to potential improvements in settlement and collateral mobility, particularly the ability to move assets and collateral between clearinghouses, intermediaries and market participants more rapidly.
Drawing a comparison with the industry’s shift from manual trading practices to electronic markets, Selig said Tokenization could represent a similarly important technological transition across multiple asset classes.
The CFTC chair also indicated that regulators should avoid imposing rigid rules that could become outdated as technology develops. Instead, he said the agency would pursue principles-based regulation as onchain finance expands.
That approach could become particularly important following the Senate’s Sept. 15 vote on the CLARITY Act. The chamber rejected a cloture motion on the legislation, preventing the bill from advancing at that stage.
Selig had previously indicated that the CFTC could continue developing crypto-related rules under its existing authority if Congress failed to enact the legislation.
The SEC has also been moving toward a financial system in which securities can operate on blockchain networks.
On Sept. 17, the agency approved a temporary Innovation Exemption allowing certain Tokenized Securities Venues, or TSVs, to facilitate trading in tokenized National Market System stocks under specified conditions.
The decision represents a significant regulatory step because it allows certain digital representations of stocks to be traded through onchain venues rather than requiring every transaction to follow conventional exchange infrastructure.
SEC Chairman Paul Atkins described the move as a step toward bringing U.S. capital markets into the digital age. The exemption, however, is temporary and conditional rather than a permanent overhaul of securities-market rules.
The SEC has placed several safeguards around the program. Tokenized stocks must generally provide holders with the same rights and privileges as equivalent traditional shares. Trading is also subject to limits on eligible symbols and transaction volumes, while participating venues must meet transparency, technology and operational requirements.
The agency also requires smart contracts used by these venues to be auditable and publicly deployed on a public, permissionless distributed ledger.
The parallel actions by the CFTC and SEC suggest that the development of blockchain-based financial markets is continuing even as broader cryptocurrency legislation remains unresolved.
SEC Commissioner Mark Uyeda said Tokenization could modernize fundamental market functions, including issuance, trading, settlement, transfer and ownership records. He also pointed to potential reductions in costs, greater transparency and improved liquidity.
The SEC’s temporary exemption is designed partly as a testing ground. Regulators will be able to observe how onchain stock markets operate while collecting public feedback before deciding what longer-term regulatory changes may be appropriate.
For the CFTC, the focus is broader. Selig’s remarks place Tokenization alongside artificial intelligence and 24-hour markets as technologies regulators must prepare for rather than treat as peripheral developments.
The CFTC has also established an Innovation Task Force and announced a series of public Frontier Forums focused on emerging financial technologies. The agency says the discussions will examine how innovation can develop while maintaining market integrity and protecting participants.
For Wall Street and the wider digital-asset industry, the message is increasingly clear: Tokenization is moving from a theoretical blockchain use case toward a subject being addressed directly by U.S. financial regulators.
The immediate framework remains limited, and major questions around market structure, investor protection, custody, settlement and interoperability remain unresolved. But with both major market regulators now actively adapting their frameworks, Tokenization is becoming increasingly embedded in the policy debate over the future architecture of U.S. financial market.


Copyright © 2025 - The Bit Gazette.