
- Trending
- Comments
- Latest
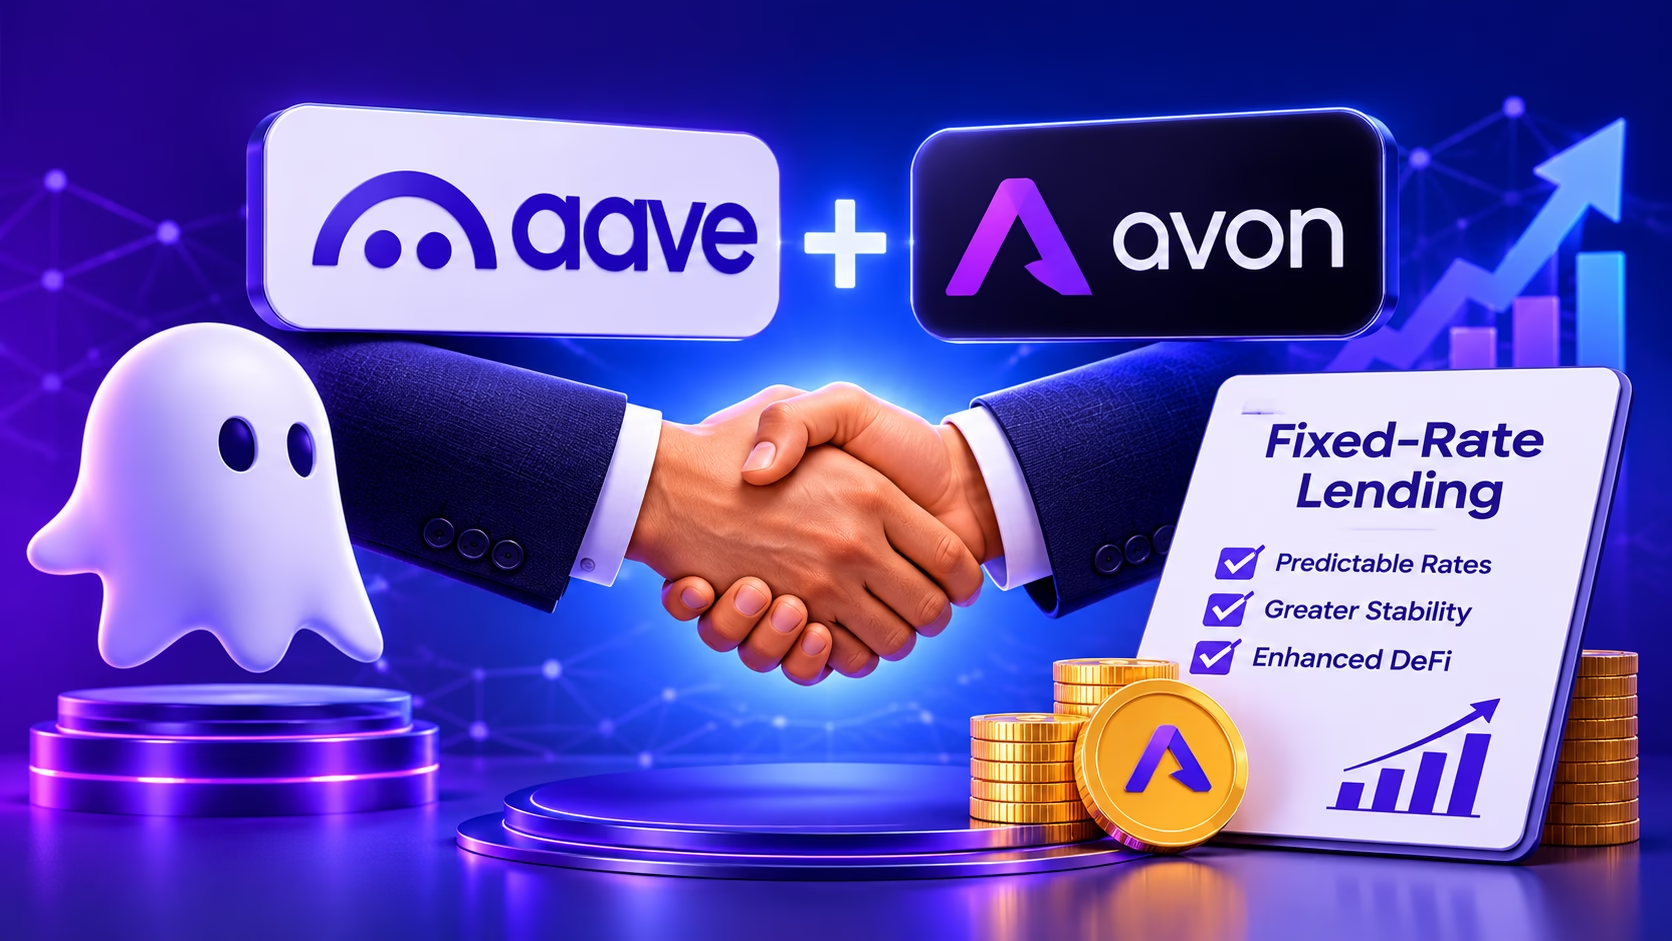
Aave Labs has acquired the team and technology behind Avon as it moves to add fixed-rate lending to its onchain lending network, the company announced on November 6, 2026. The deal includes Avon’s fixed- and floating-rate protocols, its onchain order book and domains. Financial terms and a launch date were not disclosed.
The acquisition represents more than a transfer of intellectual property. It gives Aave access to a team that has spent considerable time exploring the technical and financial challenges associated with building sophisticated credit markets on blockchain networks.
Avon was founded by Prince Sinha to bring elements of traditional credit markets into decentralized finance. Its development work focused on lending infrastructure that could accommodate different interest-rate arrangements, alongside mechanisms for managing risk across lending strategies.
Under the agreement, the Avon team will continue developing its technology within the Aave ecosystem under Aave Labs. Its responsibilities will contribute to improvements across the network and product layers, with new borrowing capabilities among the company’s stated priorities.
Aave founder and CEO Stani Kulechov described the acquisition as part of the company’s broader ambition to make established financial products accessible through decentralized infrastructure.
“Aave’s goal is to bring the best of finance to everyone, and that means offering the kinds of products users already rely on, including fixed rates,” Kulechov said in the official announcement.
He also highlighted the technical experience Avon brings, noting that its team has worked on some of the most challenging problems in onchain lending.
Sinha expressed similar enthusiasm about the opportunity to continue developing Avon’s original vision within a larger financial ecosystem.
“We started Avon to bring the depth of global credit markets onchain, and Aave is the best place to continue that work,” he said, pointing to the potential to reach institutions, fintech companies and everyday users at scale.
However, neither statement confirms that an operational lending market is ready for public use.
One of the biggest challenges facing decentralized lending platforms is the uncertainty surrounding borrowing costs. Many existing DeFi lending markets rely on variable interest rates that respond to changes in liquidity demand.
Aave’s documented interest-rate model uses utilization curves to determine borrowing costs. Utilization measures how much of a particular asset’s available liquidity has been borrowed. When borrowing demand increases, interest rates rise, encouraging additional deposits and repayments. When liquidity becomes more abundant, borrowing costs generally decrease.
This approach helps lending markets respond to changing supply and demand. However, it also means borrowers cannot necessarily predict how much interest they will pay throughout an extended borrowing period.
Fixed-Rate Lending introduces a different arrangement. Instead of allowing borrowing costs to change continuously with market utilization, a borrower agrees to an interest rate for a specified period. This provides greater visibility into financing expenses and makes it easier to plan repayments.
For lenders, the arrangement can also offer a more predictable return. However, committing funds for a defined period introduces additional considerations, particularly when lenders want to withdraw their capital before maturity.
This is where Avon’s onchain order book becomes particularly important.
Traditional financial markets frequently rely on order books to connect buyers and sellers at agreed prices. Avon developed a similar infrastructure for decentralized lending, allowing lending opportunities to be organized around more sophisticated market structures.
Rather than depending exclusively on pooled liquidity and utilization-based pricing, an order-book model can help match borrowers and lenders according to their preferred rates and lending terms.
Such infrastructure could provide greater flexibility when building credit products with different maturities, pricing arrangements and risk characteristics.
However, implementing these markets onchain requires careful consideration of liquidity, collateral valuation and liquidation mechanisms.
A lender committing capital for a fixed period may not have the same immediate withdrawal flexibility available in a conventional liquidity pool. If that lender needs to exit early, the protocol must provide a reliable mechanism for transferring or valuing the outstanding lending position.
Liquidation introduces another challenge. Aave’s existing lending infrastructure relies on collateral values and position health to determine when a loan becomes eligible for liquidation. A new term-based lending arrangement would need to account for outstanding interest obligations and the additional risks associated with maturity.
Avon’s previous work on interest-rate pricing, risk isolation and lending market design could help Aave address these requirements.
Nevertheless, the acquisition announcement does not explain precisely how the order book will integrate with Aave’s existing lending infrastructure.
The acquisition strengthens Aave’s ambitions to serve a broader range of participants, particularly institutions and fintech businesses that require more predictable financing arrangements.
For larger financial organizations, borrowing costs and repayment schedules are important considerations when evaluating lending infrastructure. More predictable rates could make decentralized credit products easier to incorporate into financial planning and treasury operations.
The opportunity also extends to individual borrowers who want greater certainty when accessing liquidity against their digital assets.
Aave’s existing scale provides a substantial foundation for introducing additional financial products. However, the success of the acquisition will depend on how effectively the company integrates Avon’s technology while maintaining liquidity, security and sustainable lending conditions.
The market will also be watching for details about eligible collateral, supported blockchain networks, loan maturities and the eventual relationship between the new infrastructure and Aave’s existing markets.
Meanwhile, AAVE recorded a trading range of $119.20 to $171.52 during the 30 days leading up to November 7, 2026, according to the CoinGecko data referenced in the supplied market chart. This range alone does not establish that the acquisition influenced the token’s performance.
For now, the deal represents a strategic investment in lending infrastructure rather than an immediate change to the borrowing experience.
Aave has secured the people and technology needed to explore a broader credit offering. Whether that translates into a fully operational Fixed-Rate Lending product will depend on the technical implementation and subsequent product announcements.


Copyright © 2025 - The Bit Gazette.