




- Trending
- Comments
- Latest

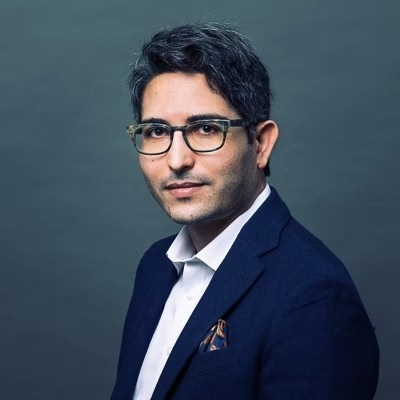
Dr. Daniele D’Alvia
Director of the Institute of Banking and Finance Law
Centre for Commercial Law Studies (CCLS)
Queen Mary University of London
This guest opinion was written by Dr Daniele D’Alvia and published by The Bit Gazette editorial team.
Imagine being told that Bitcoin worth billions has been seized after a fraud that swallowed your savings. You might think the hardest question has been answered: the assets have been found. However, for the victims trying to recover them, the real legal fight may only have begun.
That is the unsettling lesson of a High Court judgment delivered in London on 12 October 2026. The case involves more than 61,000 Bitcoin linked to a Ponzi scheme orchestrated by Zhimin Qian in China between 2014 and 2017. British authorities recovered the assets; investors have come to an English court claiming that some of that property belongs to them.
Mr. Justice Turner ruled that Chinese law, not English law, governs the underlying rights on which those investors rely. He did not decide who owns the Bitcoin. Nor did he decide how much, if anything, individual claimants will recover. Those questions are for another stage. The distinction matters.
I see something more important here than a fight over one extraordinary haul of cryptocurrency. The case exposes what I call the sovereign recovery gap: the distance between an asset’s freedom to move across borders and an investor’s ability to enforce rights when something goes wrong.
Crypto has become very good at solving the first problem. It remains remarkably poor at solving the second.
Consider the legal irony. English law recognises Bitcoin as property; the court itself noted the Property (Digital Assets etc) Act 2025. Yet, as the judge explained, calling an asset “property” is not a magic answer to the question of which country’s law applies. A claimant seeking protection under section 281 of the Proceeds of Crime Act must establish a proprietary interest in the assets, not merely a personal claim against a fraudster for repayment.
A blockchain can show how digital assets move between addresses. However, it cannot, by itself, determine who legally owns those assets, even where someone’s savings financed their acquisition. A creditor may be owed money without having a proprietary claim to a particular asset. In cross-border fraud, that difference may decide everything.
And that is where this judgement reaches far beyond Bitcoin.
“It requires taking private international law as seriously as smart contract code.”
My research on foreign stablecoins and monetary sovereignty has led me to a deceptively simple question: when a digital token circulates internationally, which legal promise travels with it?
Take a dollar-denominated stablecoin issued outside Europe, acquired through a decentralised exchange and held by a user in the EU. The token might move in seconds. But suppose the issuer fails, a custodian freezes assets, or a court in another country takes control of reserves.
Does the holder have a direct redemption claim? Against whom? In which jurisdiction? Is the right effective in insolvency, or does it become an ordinary unsecured claim?
These are not identical to the issues in Qian. Bitcoin has no issuer promising redemption, and the High Court did not rule on stablecoins or decentralised finance. But the underlying warning is similar: technical control of a token and legal protection of the person holding it are different things.
The EU’s Markets in Crypto-Assets Regulation, MiCAR, has made real progress. For e-money tokens within its framework, it expressly provides a claim against the issuer and a right to redemption at par. That is meaningful.
Yet a right written in a rulebook still needs an effective path to enforcement, especially where issuers, intermediaries, reserves and customers sit in different countries. Foreign stablecoins make that question impossible to ignore.
I would like regulators to ask a tougher question before celebrating another compliance licence or proof-of-reserves report: can the investor actually recover?
We need what I would call a recovery rights test. Issuers and intermediaries should explain in plain language which law governs a holder’s claim, who is legally obliged to pay, what happens if assets are frozen or a provider fails, and where a judgment could be enforced.
Regulators should press for cross-border arrangements that preserve transaction records, recognise legitimate claims and prevent victims becoming an afterthought in asset-recovery proceedings.
None of this requires the fantasy of a single global crypto court. It requires taking private international law as seriously as smart contract code.
One final point: we should resist turning this case into a contest over whether Britain or China deserves a Bitcoin windfall. The people who lost money in the underlying fraud should not disappear behind a geopolitical headline. Their prospects remain unresolved, and the legal process must run its course.
Crypto’s next great test is not whether digital assets can cross borders. We already know they can. It is whether the rights of people harmed along the way can cross borders too.
This is a guest opinion. The views expressed are the author’s own and do not necessarily reflect those of The Bit Gazette.


Copyright © 2025 - The Bit Gazette.

