- Trending
- Comments
- Latest
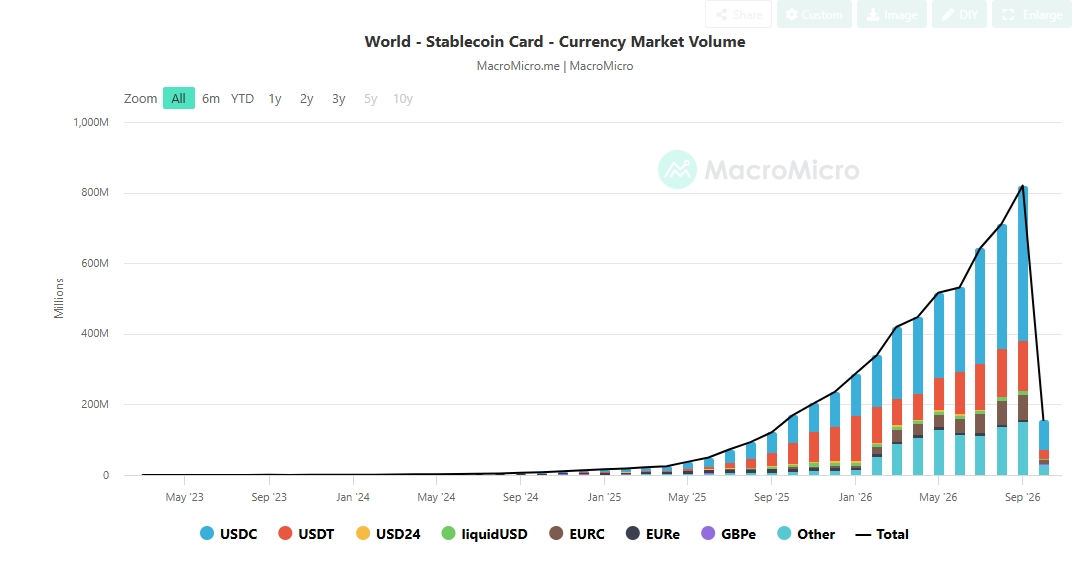
Crypto card volume rose 33% to $4.31 billion in the third quarter of 2026, up from $3.24 billion in the previous quarter, as regulated stablecoins took a bigger share of everyday spending. USDC led the shift, with September card payments of more than $439 million, over three times USDT’s, according to MacroMicro data.
Tether’s Plasma payment network was among the reported growth drivers, recording a 350% increase in volume during the quarter. Meanwhile, USDC gained ground in card payments as demand for regulated stablecoins and transparent asset backing influenced how users accessed digital assets for spending.
The trend is also affecting investment in the cryptocurrency sector. Data attributed to CryptoRank showed that payments, exchanges and brokerages accounted for 71.6% of venture capital funding in the third quarter, signalling a shift toward businesses focused on financial services and practical applications.
Together, these developments suggest that crypto-linked payments are becoming a more prominent part of the digital asset economy, even as other cryptocurrency sectors experience changing investment priorities.
Crypto card volume climbed from $3.24 billion in the second quarter to $4.31 billion in the third quarter, representing an increase of approximately $1.07 billion.
The expansion follows a broader rise in stablecoin payment activity that has continued since 2024. While cryptocurrency prices and market sentiment have experienced periods of weakness, demand for stablecoins as a means of transferring and spending value has continued to develop.
Stablecoins are designed to maintain relatively stable prices, commonly by tracking traditional currencies such as the US dollar. Their price stability makes them useful for transactions where consumers and businesses want to avoid the volatility associated with assets such as Bitcoin.
Crypto-linked payment cards allow users to spend digital assets through familiar payment channels. Depending on the provider, the underlying cryptocurrency may be converted into a conventional currency when a transaction occurs.
This arrangement can make digital assets more accessible to consumers who want to use cryptocurrency without directly managing blockchain transactions at the point of purchase.
The latest figures suggest that crypto card volume is benefiting from the expansion of payment infrastructure and the availability of additional digital assets. However, the reported quarterly increase does not establish how much of the activity represents new consumer adoption rather than higher spending by existing users.
Plasma, Tether’s payment-focused network, recorded a reported 350% increase in volume during the quarter, making it one of the notable contributors to the broader expansion.
Blockchain networks also recorded varying levels of payment activity. TRON, which serves as a major network for USDT transfers, registered quarterly payment-volume growth of 23.2%, according to the supplied report.
TRON, Base and BNB Chain collectively accounted for nearly half of stablecoin card payments, illustrating the concentration of activity across several established blockchain ecosystems.
Ethereum continues to serve as an important network for stablecoin transactions, while Solana has attracted additional users through its expanding address base and activity across trading and decentralised finance.
These networks compete to support transfers and applications by offering different combinations of transaction costs, processing speeds, liquidity and ecosystem services.
For payment providers, access to established stablecoin liquidity can help simplify the movement of funds between digital asset platforms and consumer payment products.
USDC has emerged as a significant driver of growth in crypto-linked card payments, according to the supplied report, which points to rising demand for regulatory compliance and greater transparency around asset backing.
The shift comes as stablecoin rules develop across major markets. The European Union’s Markets in Crypto-Assets Regulation, commonly known as MiCA, introduced a regulatory framework for crypto-assets and stablecoin issuers. In the United States, the GENIUS Act established a federal framework for payment stablecoins, although implementation and compliance requirements remain relevant to how the framework operates in practice.
These developments have increased attention on the regulatory status of stablecoins used in financial services.
USDC, issued by Circle, has benefited from its positioning as a regulated dollar-backed stablecoin. The asset has increasingly featured in payment applications and services seeking to operate within established compliance frameworks.
USDT, issued by Tether, nevertheless remains a major stablecoin for cryptocurrency transfers, peer-to-peer transactions and activity across digital asset markets.
The distinction is important because stablecoin supply and total transfer activity do not necessarily translate directly into card payment usage. An asset may dominate trading and wallet transfers while another captures a greater share of transactions made through payment cards.
The supplied report places USDC’s circulating supply at approximately $75 billion, including around $6.75 billion issued on Solana.
In September 2026, USDC card payments reportedly exceeded $439 million, more than three times the corresponding usage of USDT.
That comparison suggests that USDC is gaining traction in the payment segment, even though USDT remains widely used elsewhere in the cryptocurrency market.
The development could influence crypto card volume if payment providers continue to favour stablecoins that meet their regulatory and operational requirements.
However, the figures do not establish that USDC’s growth has come entirely at USDT’s expense. The two assets serve multiple markets, and changes in card usage may reflect differences in platform availability, user preferences and transaction costs.
Stablecoin payments are also expanding beyond card transactions. The report cited adjusted payment volumes exceeding $54 billion in September, although the precise methodology used to calculate that figure was not provided.
Other major stablecoin use cases include decentralised finance, decentralised exchange routing and transfers within cryptocurrency protocols.
As a result, growth in payment cards represents one part of a broader shift toward using stablecoins for financial activity rather than holding them solely as trading instruments.
The expansion of cryptocurrency payments is also reflected in venture capital investment, with investors increasingly directing funding toward payment applications, exchanges and brokerage services.
According to figures attributed to CryptoRank, companies in these categories accounted for 71.6% of cryptocurrency venture capital funding during the third quarter of 2026.
The report put total funding at $2.26 billion across 127 investment rounds during the quarter.
The figures point to a shift from earlier investment waves that focused heavily on speculative digital assets, including non-fungible tokens and meme coins, toward businesses developing financial infrastructure and consumer-facing products.
Payment applications can provide investors with a different growth proposition from projects whose activity depends primarily on token prices or short-lived market trends.
Companies operating in payments may generate revenue through transaction fees, exchange services, card programmes and other financial products. Their performance can therefore depend on transaction activity and customer retention as well as broader cryptocurrency market conditions.
Established ecosystems have also continued to attract capital. The supplied report identified Crypto.com among the existing payment platforms receiving increased investment attention.
Across the past two quarters, payment-focused projects reportedly raised approximately $1 billion, making payments the second-largest category in cryptocurrency venture capital funding over that period.
Prediction markets ranked first, attracting approximately $2 billion, according to the same report.
The investment figures suggest that venture capital interest is broadening beyond token issuance and trading speculation. Investors are also looking at services that connect digital assets with established financial activities.
The relationship between funding and crypto card volume is not necessarily direct, however. Capital raised by a payment company does not automatically translate into higher transaction activity, and funding totals can fluctuate significantly depending on the size and timing of individual deals.
Nevertheless, the combination of rising card payments, expanding stablecoin use and continued investment in payment infrastructure points to growing interest in the sector.

Copyright © 2025 - The Bit Gazette.