- Trending
- Comments
- Latest
The US Office of the Comptroller of the Currency says nine of the country’s largest banks kept policies that could cut off lawful businesses, including crypto firms, between 2020 and September 2025.
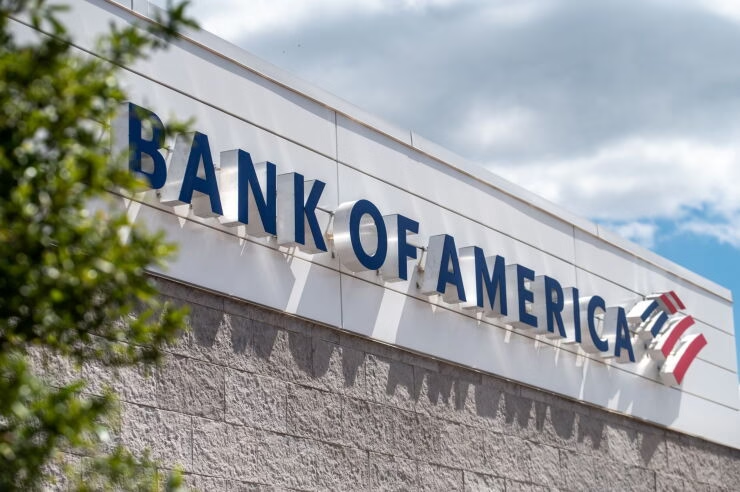
The OCC named JPMorgan Chase, Bank of America, Citibank, Wells Fargo and five others in a report published October 14. Comptroller Jonathan Gould called it “irrefutable evidence” of debanking.
The OCC said its review identified broad reputational-risk policies that lacked clear standards and objective, risk-based criteria. According to the regulator, these policies disadvantaged some customers because of their political, religious or social views, or because of the lawful activities of their businesses.
The review involved nearly 100,000 complaints to OCC-regulated institutions. The agency also received approximately 50,000 documents, comprising about 420,000 pages, covering banks’ policies, procedures, practices and individual customer decisions.
OCC Comptroller Jonathan V. Gould described the findings as evidence of a wider problem in the banking system.
“Today’s report provides irrefutable evidence that the nation’s largest banks have denied, debanked and discriminated against customers and lawful businesses,” Gould said in the regulator’s October 14 announcement.
He added that access to banking should not depend on customers’ beliefs or affiliations.
The report identified digital-asset activities among several business categories affected by public and nonpublic banking restrictions. For cryptocurrency companies, access to conventional banking remains important for handling customer deposits, paying employees, receiving business revenue and converting between digital assets and government-issued currencies.
A bank account closure or refusal to establish a banking relationship can therefore create operational difficulties for an exchange, stablecoin issuer or other digital-asset business, even when the business is operating lawfully.
Still, the OCC’s findings should not be interpreted as proof that every bank decision involving a cryptocurrency customer was politically motivated. Banks must also consider legitimate concerns involving financial crime, compliance obligations and individual customer risk. The dispute concerns whether those assessments were applied objectively or whether broad policies unfairly excluded entire categories of lawful businesses.
The phrase Operation Chokepoint 2.0 became prominent among cryptocurrency executives and industry advocates who argued that federal banking regulators made it increasingly difficult for digital-asset companies to maintain banking relationships.
The controversy intensified as crypto businesses reported difficulties accessing financial institutions and regulators scrutinized banks’ exposure to digital assets. Industry critics argued that supervisory pressure could discourage banks from serving the sector even without a formal prohibition on cryptocurrency-related banking.
In December 2025, the House Financial Services Committee’s Republican staff released a report titled Operation Choke Point 2.0: Biden’s Debanking of Digital Assets. The congressional report alleged that federal regulators used vague rules, informal guidance and enforcement pressure to discourage banks from serving digital-asset companies.
The committee said its investigation identified at least 30 digital-asset entities or individuals that lost access to financial services. That figure reflects the congressional report’s findings rather than a determination that every case involved unlawful discrimination.
The OCC subsequently addressed the controversy in a December 1, 2025, statement responding to the congressional report. Gould said the report supported concerns about regulatory pressure on financial institutions serving digital assets.
“The congressional staff report on the Biden Administration’s coordinated effort to debank digital assets confirms what many have long suspected,” Gould said in the OCC statement.
He argued that regulatory actions had discouraged or prevented some institutions within the regulated banking system from engaging with digital assets.
The distinction between the congressional allegations and the OCC’s broader bank review remains important. The October 2026 report identifies policies that could have influenced access to financial services across multiple sectors. It does not, by itself, establish that all nine banks acted under a centrally coordinated directive to exclude cryptocurrency businesses.
The findings nevertheless add weight to calls for clearer standards governing how regulators and banks evaluate lawful industries.
The October report forms part of the Trump administration’s broader effort to address alleged discrimination in banking. President Donald Trump issued an executive order titled Guaranteeing Fair Access to Banking for All Americans, directing federal agencies to examine whether financial institutions restrict services on prohibited or inappropriate grounds.
The OCC has already announced changes intended to reduce the role of reputational risk in bank supervision. In September 2025, it said it was removing references to reputational risk from its handbooks and guidance documents. The agency also worked with the Federal Deposit Insurance Corporation on a proposal to codify the removal of reputational risk from supervisory programmes.
In its December 2025 statement, the OCC said it would continue investigating whether banks unlawfully denied services to digital-asset customers and other lawful businesses.
The regulator has also emphasized that banks should make decisions through individualized, objective and risk-based analyses. That approach seeks to preserve legitimate compliance controls while limiting the use of vague standards that could exclude customers without a clear financial or legal justification.
For the cryptocurrency industry, the latest findings provide additional official evidence that banking-access restrictions deserve scrutiny. They do not settle every allegation surrounding Operation Chokepoint 2.0, but they sharpen the debate over how financial institutions balance risk management with fair access to banking.
The next question is whether the OCC’s findings will lead to concrete enforcement measures, changes in bank policies or greater transparency for businesses seeking financial services.
Until then, crypto debanking remains a significant regulatory issue at the intersection of digital-asset innovation, banking supervision and the right of lawful businesses to participate in the financial system.
Primary sources

Copyright © 2025 - The Bit Gazette.